

Recent Amendments in UAE VAT Law – Key Changes Explained
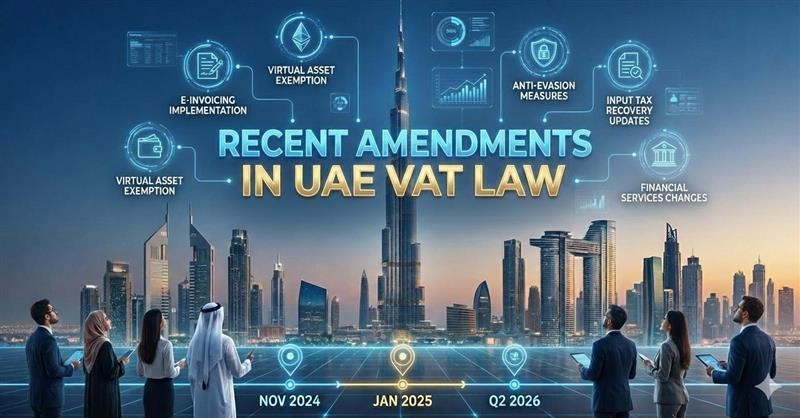
The UAE has introduced various amendments to its existing VAT Law and related tax procedures. These changes show the country’s navigation towards modernizing its tax system and aligning it with global practices. The amendments were brought in through Federal Decree Law No. 16 of 2025 (updating the VAT Law) and Federal Decree Law No. 17 of 2025 (amending the Tax Procedures Law). Highlights of the VAT law amendments: Earlier Position:The previous VAT law provided that when a UAE business applied the reverse charge mechanism, the taxable person was required to issue a self-invoice for the import of goods or services. Amendment:Taxable persons are not required to issue a self-invoice when applying the reverse charge mechanism for imports used in the business. Instead, they must retain valid supporting documents such as supplier invoices, contracts, import documentation, etc to validate the transaction for VAT purposes. This article was inserted regarding the recoverability of input tax in cases of tax evasion. Key considerations are- Many input tax claims are denied due to common VAT return filing mistakes, which businesses must now avoid under stricter recovery rules. Earlier Position:Previously, this article allowed businesses to carry forward and reclaim excess input tax without any specific time limit. Amendment:A five-year limitation period has now been introduced for utilising or reclaiming excess recoverable input tax. The five-year period will be calculated from the end of the tax period in which the excess input tax arose. Once this period expires, the taxpayer’s right to utilise, set off, or claim a refund of the excess tax will lapse. Taxpayers whose five-year refund period has already expired, or will expire within one year from 1 January 2026, can still apply for a refund until 1 January 2027. This option is available under the transitional rule introduced in the amended Tax Procedures Law. Businesses should review their VAT registration and return filing in the UAE to ensure alignment with the latest legislative changes. 4. Article 79 – Statute of Limitation This article has been cancelled. The limitation period related to excess input tax is now governed under the Tax Procedures Law effective from 1st January 2026. Highlights of the Tax Procedure amendments: Earlier Position:Previously, overpayments or tax credits could be allocated without any specific time limit. Amendment:The tax authority may now apply credits or overpayments within a maximum period of five years from the end of the relevant tax period. Voluntary Disclosures may now be filed only in the specific situations defined by the tax authority. In all other cases, errors can be corrected directly through the tax return. 3. Article 38 – Application for Refund of Credit Balance (Full provision post amendment) 4. Article 46 – Statute of Limitation (Full provision post amendment) With the recent amendments and growing complexities in the VAT law, businesses need to be more cautious and vigilant. An expert consulting firm can help you save time and add real value to your business. At BCL Globiz, we understand the complexities of your operations and are committed to providing transparent solutions suited to your business model. Connect with our experts at punith@bcl.ae
